








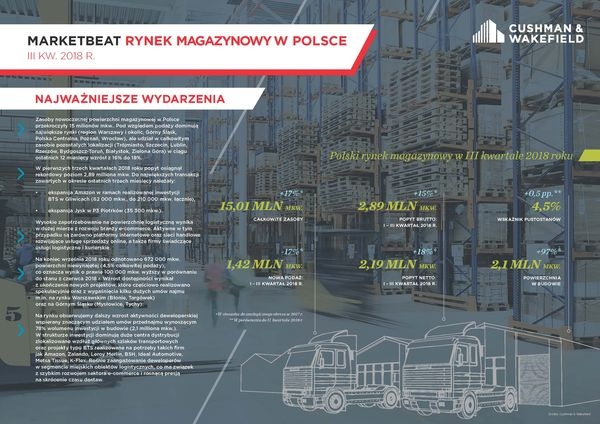
At the end of the third quarter of 2018, the total stock of the industrial and logistics space market exceeded the 15 million sqm threshold, thanks to the delivery of 1.42 million sqm of warehouse space since the beginning of the year, according to the international advisory firm Cushman & Wakefield in its “Marketbeat Poland – Q3 2018” report.
Between June and September of this year, developers completed 687,000 sqm across 23 projects. The largest amount of space was delivered in the Central Poland region (210,000 sqm), where Panattoni completed a facility for Media Expert at the Central European Logistics Hub (74,000 sqm, Panattoni) and SEGRO completed the expansion of SEGRO Logistics Park Stryków (55,000 sqm, including 39,000 sqm for Corning Optical Communications). Among the largest completed investments were also Goodman Wrocław V Logistics Center (57,000 sqm for The Hut Group), Hillwood Krosno Odrzańskie (41,500 sqm), and Panattoni Park Białystok (41,000 sqm).
Cushman & Wakefield analysts point out that the market is seeing continued growth in development activity, supported by high demand. At the end of September 2018, 2.1 million sqm remained under construction (in 61 projects), 78% of which was secured by lease agreements. The largest amount of warehouse space is being built in Central Poland (584,000 sqm), Upper Silesia (383,000 sqm), and the Warsaw region (259,000 sqm). Significant growth in stock is also expected in the northern and western parts of the country, including the Tri-City (183,000 sqm), Wrocław (145,000 sqm), and Szczecin (130,000 sqm).
Demand for modern logistics and production space in Poland in Q3 2018 remained at a high level. The volume of lease transactions amounted to 789,000 sqm, and total demand in the first three quarters reached a record level of 2.89 million sqm, which was 15% higher compared to the same period of the previous year. Traditionally, the most space was leased in the five main markets (nearly 2.18 million sqm), led by the Upper Silesia region (515,000 sqm), Central Poland (495,000 sqm), and the Warsaw area (460,000 sqm). In the transaction structure, the largest shares were held by the following sectors: logistics (33%), retail chains (17%), e-commerce (15%), and manufacturing (8%). Net demand, including new leases and expansions, amounted to 2.19 million sqm (76% of total demand), while the remaining 700,000 sqm (24%) consisted of renegotiations. The largest transactions concluded in the last three months were Amazon’s expansion as part of a BTS investment in Gliwice (60,000 sqm) and Jysk’s lease expansion at P3 Mszczonów (35,000 sqm).
At the end of September 2018, approximately 672,000 sqm of warehouse space remained vacant, representing 4.5% of total supply. The vacancy rate increased by 0.5 pp compared to Q2 of this year, but fell by 0.8 pp compared to the level from a year ago. The most available space was recorded in four markets: the Warsaw area (184,000 sqm), Upper Silesia (178,000 sqm), Poznań (86,000 sqm), and Warsaw city (78,000 sqm). Conversely, no vacancies were recorded in Szczecin, Western Poland, and Bydgoszcz-Toruń. The highest vacancy rate remained in Warsaw (10.6%, an increase of 0.2 pp compared to the end of Q2 2018) and Kraków (7.9%, -0.5 pp), while the lowest values were recorded in the Tri-City (1.4%, +1.3 pp) and Central Poland (1.5%, +1.1 pp).
The highest headline and effective rents consistently apply in Warsaw (max. 5.25 EUR/sqm/month for Small Business Units and max. 4.50 EUR/sqm/month) and in Kraków (max. 4.50 EUR/sqm/month and 4.00 EUR/sqm/month). In other markets, for larger BIG-BOX warehouse modules (above 2,000 – 5,000 sqm), headline rent rates are significantly lower (max. 3.60 EUR/sqm/month). Meanwhile, the effective rent usually does not exceed 3.20 EUR/sqm/month.
The full report is available below in PDF format.
The report comes from the website: http://media.pl.cushmanwakefield.com.pl/pr/410775/raport-cushman-wakefield-rynek-powierzchni-przemyslowych-i-logistyczny