









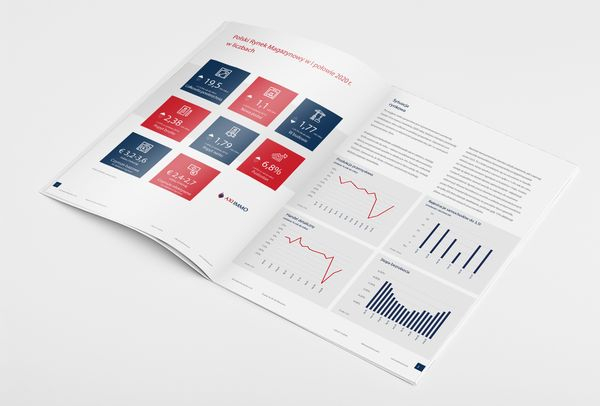
The Polish warehouse market continues to be on an upward trend after the first half of 2020. The COVID-19 pandemic did not affect demand-side results. From January to the end of June, 2.38 million sqm of modern production and logistics space was leased. However, comparing only gross demand in Q2 2020 year-on-year, it increased by over 50% to 1.36 million sqm. Such good results are the effect of high activity from tenants in the e-commerce sector, including large BTS transactions. AXI IMMO presents its latest publication, the report “Polish Warehouse Market in H1 2020”.
The first half of the year in the warehouse market proved that the global shock caused by the COVID-19 pandemic did not have such a significant impact on this sector. The volume of investment transactions in Poland reached a record high of nearly 1.2 billion euros and accounted for almost 40% of the total capital invested in the country. Among the selected largest transactions completed in Q2 2020 were, among others, the sale of the P3 Mszczonów park (158,000 sqm) to Elite Partners Capital, as well as the purchase by Polish Logistics LLP, an investment platform established by REINO Capital, IO AM, and the Grosvenor Group, of the Logistic City Piotrków Trybunalski logistics center with an area of 135,000 sqm. Currently, the best big-box facilities are valued at 6.25%, and prime properties in the Warsaw city zone at 5.5%. Maintaining capitalization rates at an unchanged level is a result of the stability and security of business operations, as well as strong demand, which for many foreign funds is an argument for investing in this asset class in Poland.
– Despite the expected difficulties in the investment market in the warehouse sector in Poland, we could look with optimism at subsequent reports of concluded transactions. As a result, the first half of 2020 was closed with a record result of around 1.2 billion euros. In the coming quarters, we will observe a further redirection of investor interest from the retail and office sectors to the warehouse sector. The availability of quality products on the market will remain a challenge – adds Renata Osiecka, Managing Partner, AXI IMMO.
Unabated demand in the warehouse market
In the first half of 2020, record tenant activity was recorded. In the analyzed period, gross demand amounted to 2.38 million sqm of warehouse space (+25% y/y), and the most attractive markets included Warsaw (602.4 thousand sqm), Upper Silesia and Central Poland (396 thousand sqm each), and Poznań (257 thousand sqm). Moreover, in the second quarter of 2020 alone, 1.36 million sqm was leased, which is over 50% more than in the same period a year earlier. Meanwhile, 326,000 sqm of space was leased under short-term contracts in the first half of the year. In the total volume of lease transactions, the highest share was accounted for by new contracts and expansions, which made up 75% of all signed agreements. The most active sectors in H1 2020 were: 25.5% logistics, 18% electronics/home appliances, 14.5% retail chains, 14.4% e-commerce, and 7.5% manufacturing.
Among the largest transactions closed in H1 2020, it is worth mentioning Panattoni BTS Świebodzin for over 200,000 sqm for a confidential e-commerce tenant, Euro Net in Prologis Park Janki for 73,400 sqm, Amazon in Hillwood Łódź Górna for 72,900 sqm, and two confidential tenants, the first of which represents the clothing industry and will occupy 67,000 sqm in Panattoni Park Czeladź IV, while the second leased 51,900 sqm in Exeter Park Stryków.
– One of the long-term consequences of the COVID-19 pandemic that is redefining the warehouse market is the shift of trade to the Internet. We do not yet know the decisions of all tenants, but we expect that those companies that decide to give up retail space but want to remain on the Polish market will decide to lease warehouse space. Therefore, absence from a shopping center or retail park will not mean a complete withdrawal of the company from the Polish market. This, in turn, will be an additional stimulus for the development of the warehouse sector, including smaller warehouse formats, such as projects in the SBU formula, which, in addition to warehouse space, can offer space as a showroom – says Anna Głowacz, Director in the Logistics and Industrial Department, AXI IMMO.
H2 2020 marked by reduced development activity?
At the end of June 2020, developers delivered approx. 1.1 million sqm of new space (+9.6% y/y), bringing total warehouse stock in Poland to nearly 19.5 million sqm (+15.9% y/y). The most investments were delivered in the Warsaw region (over 325,000 sqm), Lower Silesia (200,000 sqm), and Upper Silesia (192,000 sqm). Among the largest projects delivered in H1 2020 were Panattoni A2 Warsaw Park for 103,670 sqm, BTS P3 PepsiCo Mszczonów for 58,500 sqm, and Hillwood Wrocław Wschód II for 52,400 sqm. In the context of new supply, approx. 1.77 million sqm is currently under construction (-24% y/y), mainly in the Warsaw region and in Lower and Upper Silesia. Supply constraints are caused by greater caution related to the uncertain market situation and higher requirements related to project financing, which can be observed, among other things, in the decline in speculative construction. At the end of June, its share was 33.6%, compared to 45.3% at the end of March this year. This situation also affects the vacancy rate, which is currently 6.8% (+0.8 pp y/y). The most space available immediately is offered by the Wrocław market (10.1%), Poznań (7.4%), and Central Poland (6.9%). In the context of supply in smaller warehouse markets, it is worth following the situation in the Tri-City and Western Poland, where the total stock of these markets should increase by 29% and 71% respectively after the completion of projects under construction.
Base rents stable
In most markets, rents in the first half of 2020 remained at a stable level. Average rates in big-box facilities range from 3.20 to 3.60 euros/sqm, with Warsaw city remaining the most expensive location (from 4.80 euros/sqm). However, in terms of effective rates, a slight downward trend was visible at the end of June this year. This situation mainly concerns regions with high vacancy levels and locations with high competitiveness. The lowest effective rates can be obtained in the vicinity of Poznań and the Warsaw area (Błonie, Grodzisk Maz.).
The full report is available below in PDF format.
The report comes from the website: https://www.axiimmo.com/raporty-i-publikacje/raport-rynek-magazynowy-1-polowa-2020-r